Arizona Restoration Contractor Insurance
See How We're Different:
or Call Us:(480) 526-3222
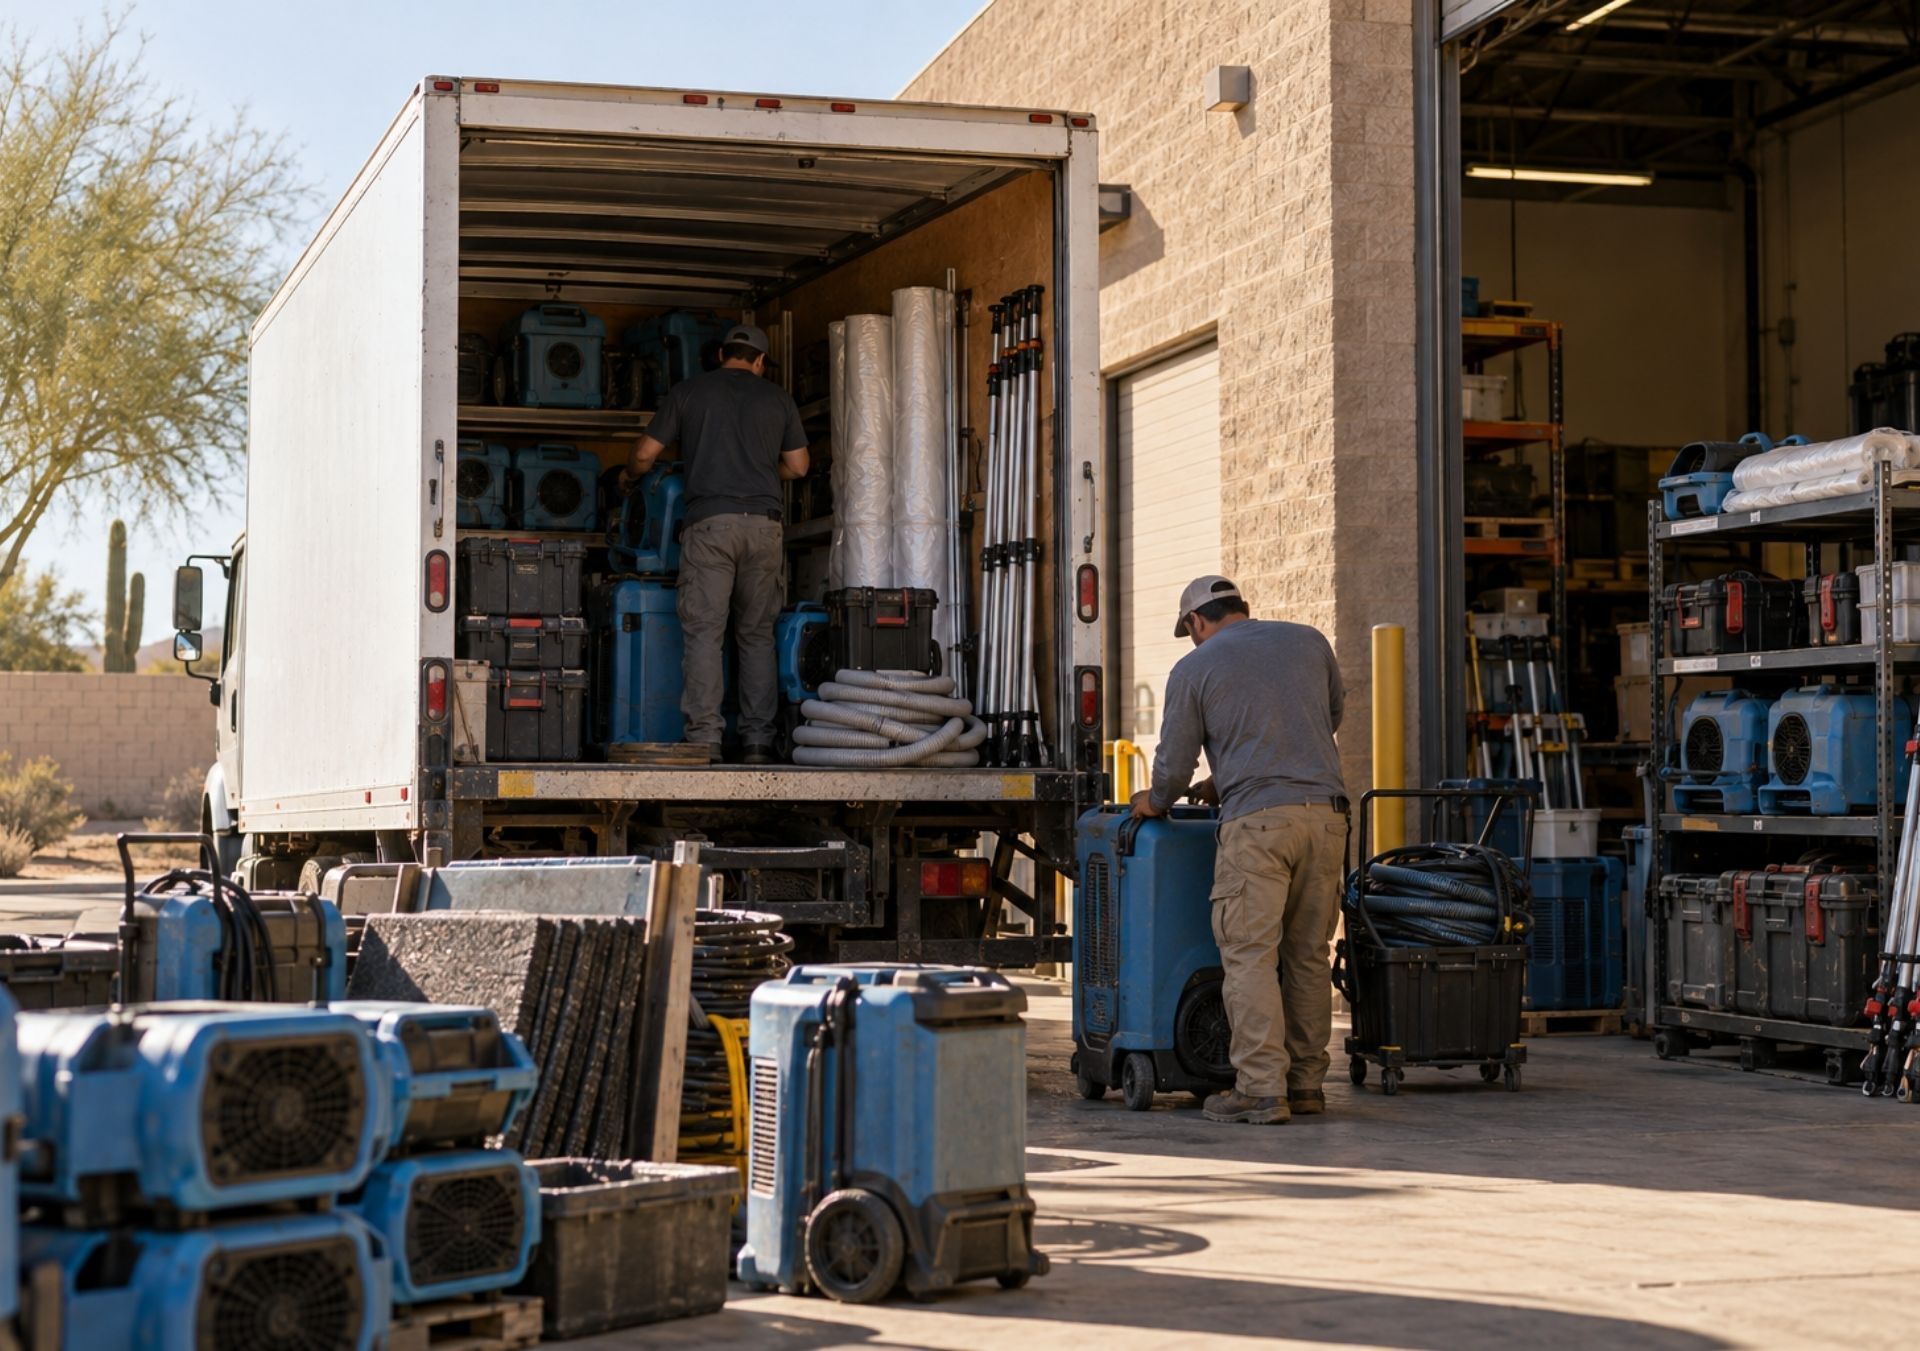
Arizona's restoration contractors face a unique combination of hazards that most general contractors never encounter. Between monsoon flooding that can dump inches of rain in a single afternoon, wildfire damage spreading through communities near Sedona and Flagstaff, and mold blooms triggered by desert humidity shifts, your insurance needs are anything but standard. A complete guide to
restoration contractor insurance in Arizona has to account for water, fire, and mold work alongside pollution liability, contents coverage, monsoon-specific claims, and workers' compensation. Getting the wrong policy - or worse, carrying gaps you don't know about - can turn a single claim into a business-ending event. The stakes are higher in 2026 than they've been in years, with new legislation reshaping how contractors and adjusters interact, carrier payment timelines stretching longer, and wildfire risk data reshaping how insurers price coverage across the state. If you're running a restoration business here, understanding exactly what your policy does and doesn't cover isn't optional.
The Unique Risk Landscape for Arizona Restoration Contractors
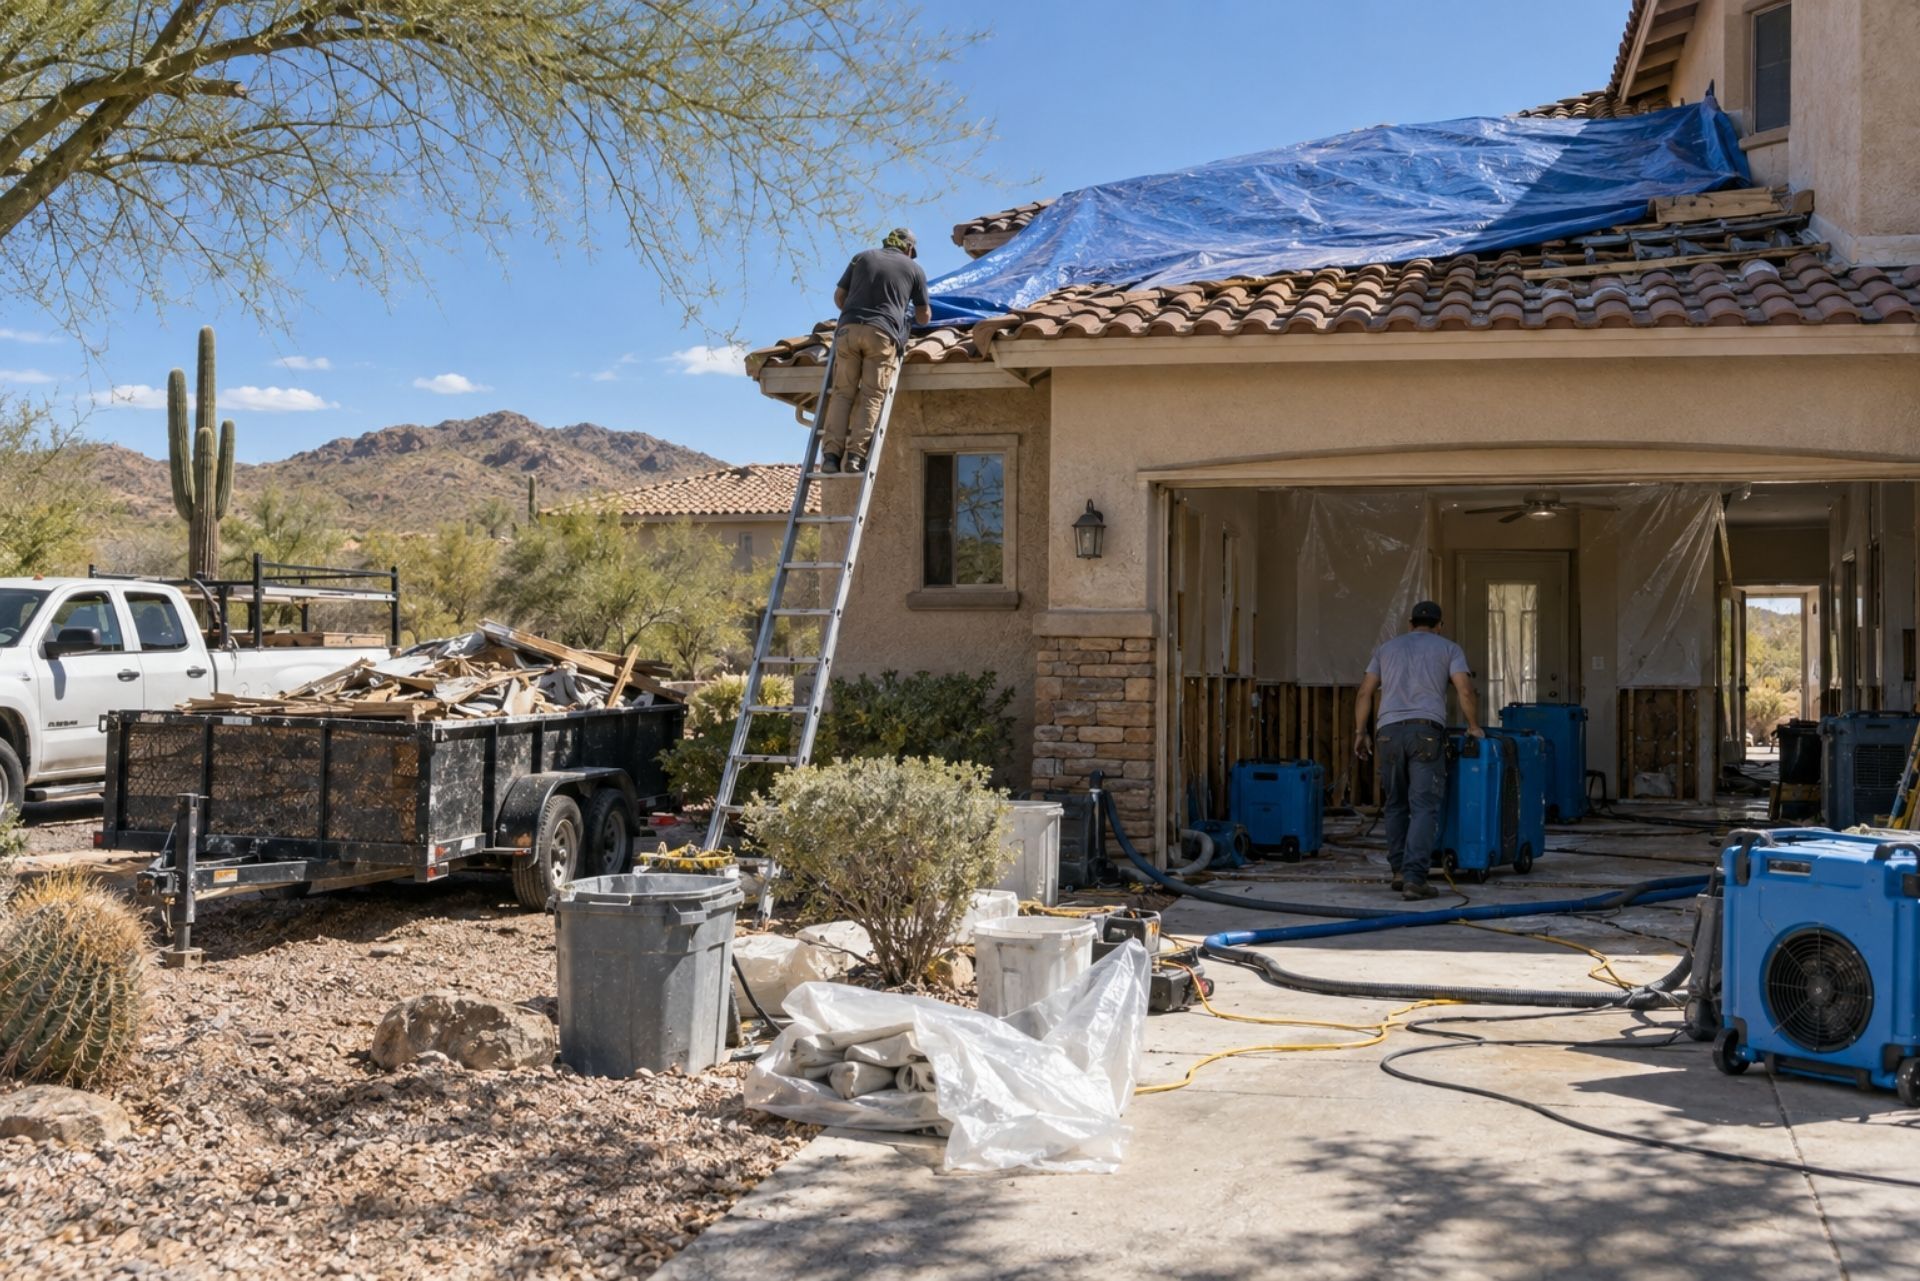
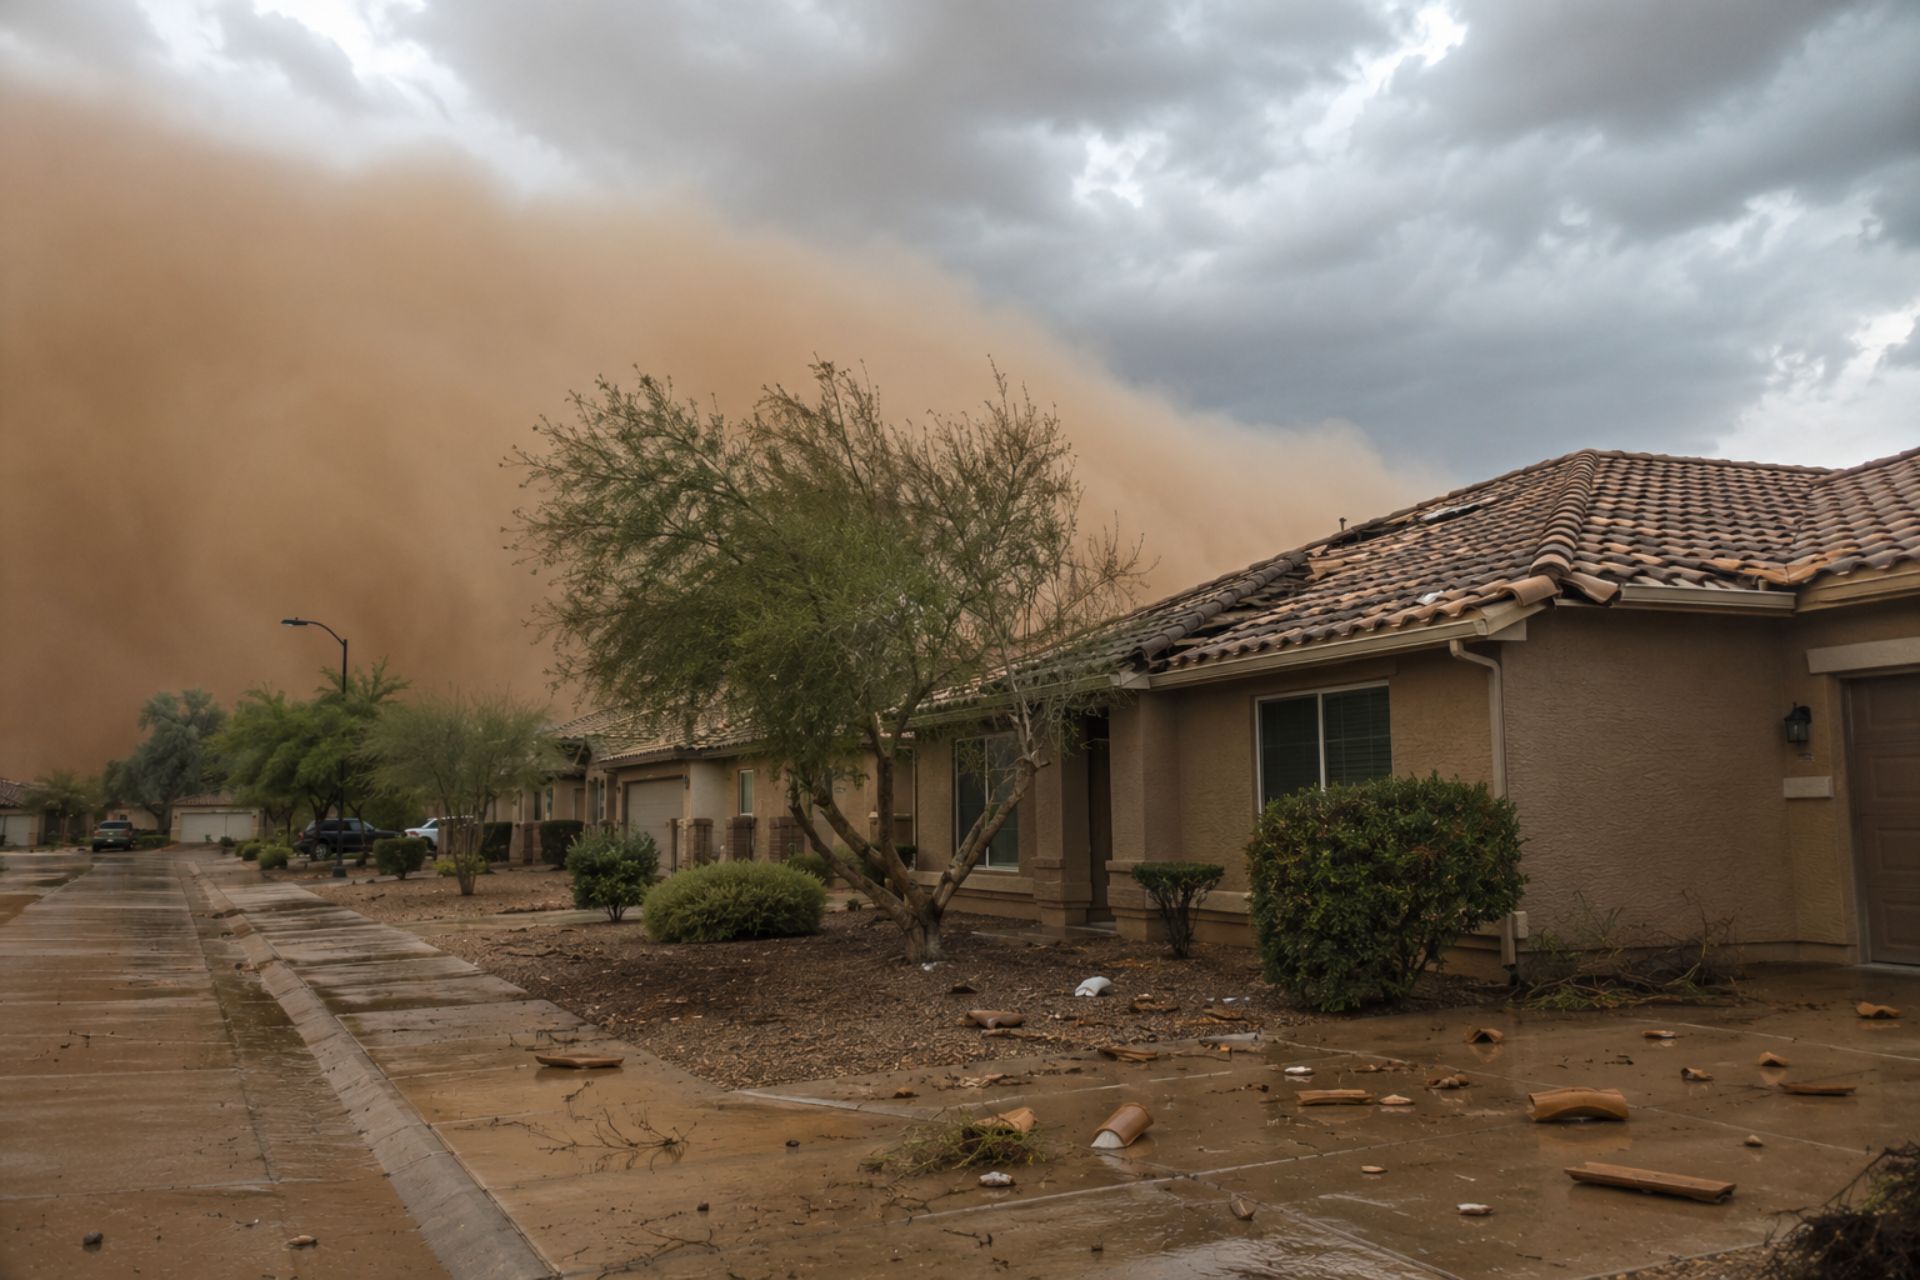
Arizona isn't just hot. It's a state where three distinct disaster profiles collide: monsoon flooding, wildfire, and the mold that follows both. The 2026 monsoon season brought above-normal precipitation that hit the Phoenix metro area and northeastern Arizona especially hard, generating a surge in water damage claims that kept restoration crews working around the clock from June through September.
Wildfire risk is equally pressing. The Pocket Fire near Sedona burned over 27,000 acres in June and July 2026, displacing residents and creating months of fire restoration work. Arizona insurers are now required to report transactional-level data for policies in high-risk wildfire areas as part of a mandatory data call covering 2025 and 2026. That means underwriters have more granular risk data than ever, and they're using it to adjust premiums and coverage terms for contractors operating in fire-prone zones.
On top of the physical hazards, restoration firms are dealing with a
cash flow crunch as carrier payment delays now stretch to 60 to 90 days as a standard timeline. Your insurance program needs to account for this financial pressure, not just the physical risks on the job site.
Essential Insurance Coverages for Water and Fire Mitigation
Every restoration contractor needs a core set of coverages, but the specifics matter more than the labels. A policy that works for a general remodeling contractor won't protect you when you're tearing out fire-damaged drywall or extracting water from a flooded commercial building.
General Liability vs. Professional Liability
General liability (GL) covers third-party bodily injury and property damage that happens during your work. If a technician accidentally damages a client's hardwood floor while setting up drying equipment, GL responds. Professional liability, on the other hand, covers errors in your professional judgment: recommending the wrong drying protocol, missing hidden moisture that leads to secondary damage, or providing a faulty scope of work.
Most restoration contractors need both. GL alone won't protect you if a homeowner sues because your moisture assessment missed a problem behind the walls. And professional liability won't cover the slip-and-fall that happens on a job site. One thing to keep in mind: primary GL pricing has stabilized in 2026, but excess liability layers remain more expensive and harder to place.
Pollution and Mold Coverage Exceptions
Standard GL policies almost always exclude pollution-related claims. That's a serious problem for restoration contractors who handle mold remediation, asbestos abatement, or sewage cleanup. You need a separate Contractors Pollution Liability (CPL) policy to cover claims arising from the release or disturbance of pollutants during your work.
The good news: CPL rates have stabilized in 2026, with expected increases of only 0% to 5%. Combined professional and pollution policies are seeing slightly higher increases of 5% to 10%, but they're still accessible. If you do both fire and mold work, a combined policy often makes more financial sense than purchasing each coverage separately.
Comparison of Standard vs. Specialized Restoration Policies
Not all contractor policies are created equal. Here's how a standard general contractor policy stacks up against a specialized restoration contractor policy:
| Coverage Area | Standard GC Policy | Specialized Restoration Policy |
|---|---|---|
| Pollution/Mold | Excluded | Included or available as endorsement |
| Contents in Your Care | Limited or excluded | Bailee's coverage included |
| Professional Errors | Not covered | Professional liability built in |
| Equipment/Tools | Basic inland marine | Specialized equipment floater |
| Emergency Response | Standard terms | Expedited claims handling |
| Subcontractor Coverage | Varies | Tailored to sub-heavy restoration model |
The catch is that specialized policies cost more upfront. But a single uncovered mold claim or a dispute over damaged client belongings can easily exceed the premium difference for an entire year. Restoration work involves handling other people's property, working with hazardous materials, and making professional judgments under time pressure. A generic policy simply wasn't designed for those exposures.
Arizona State Requirements and Workers' Compensation
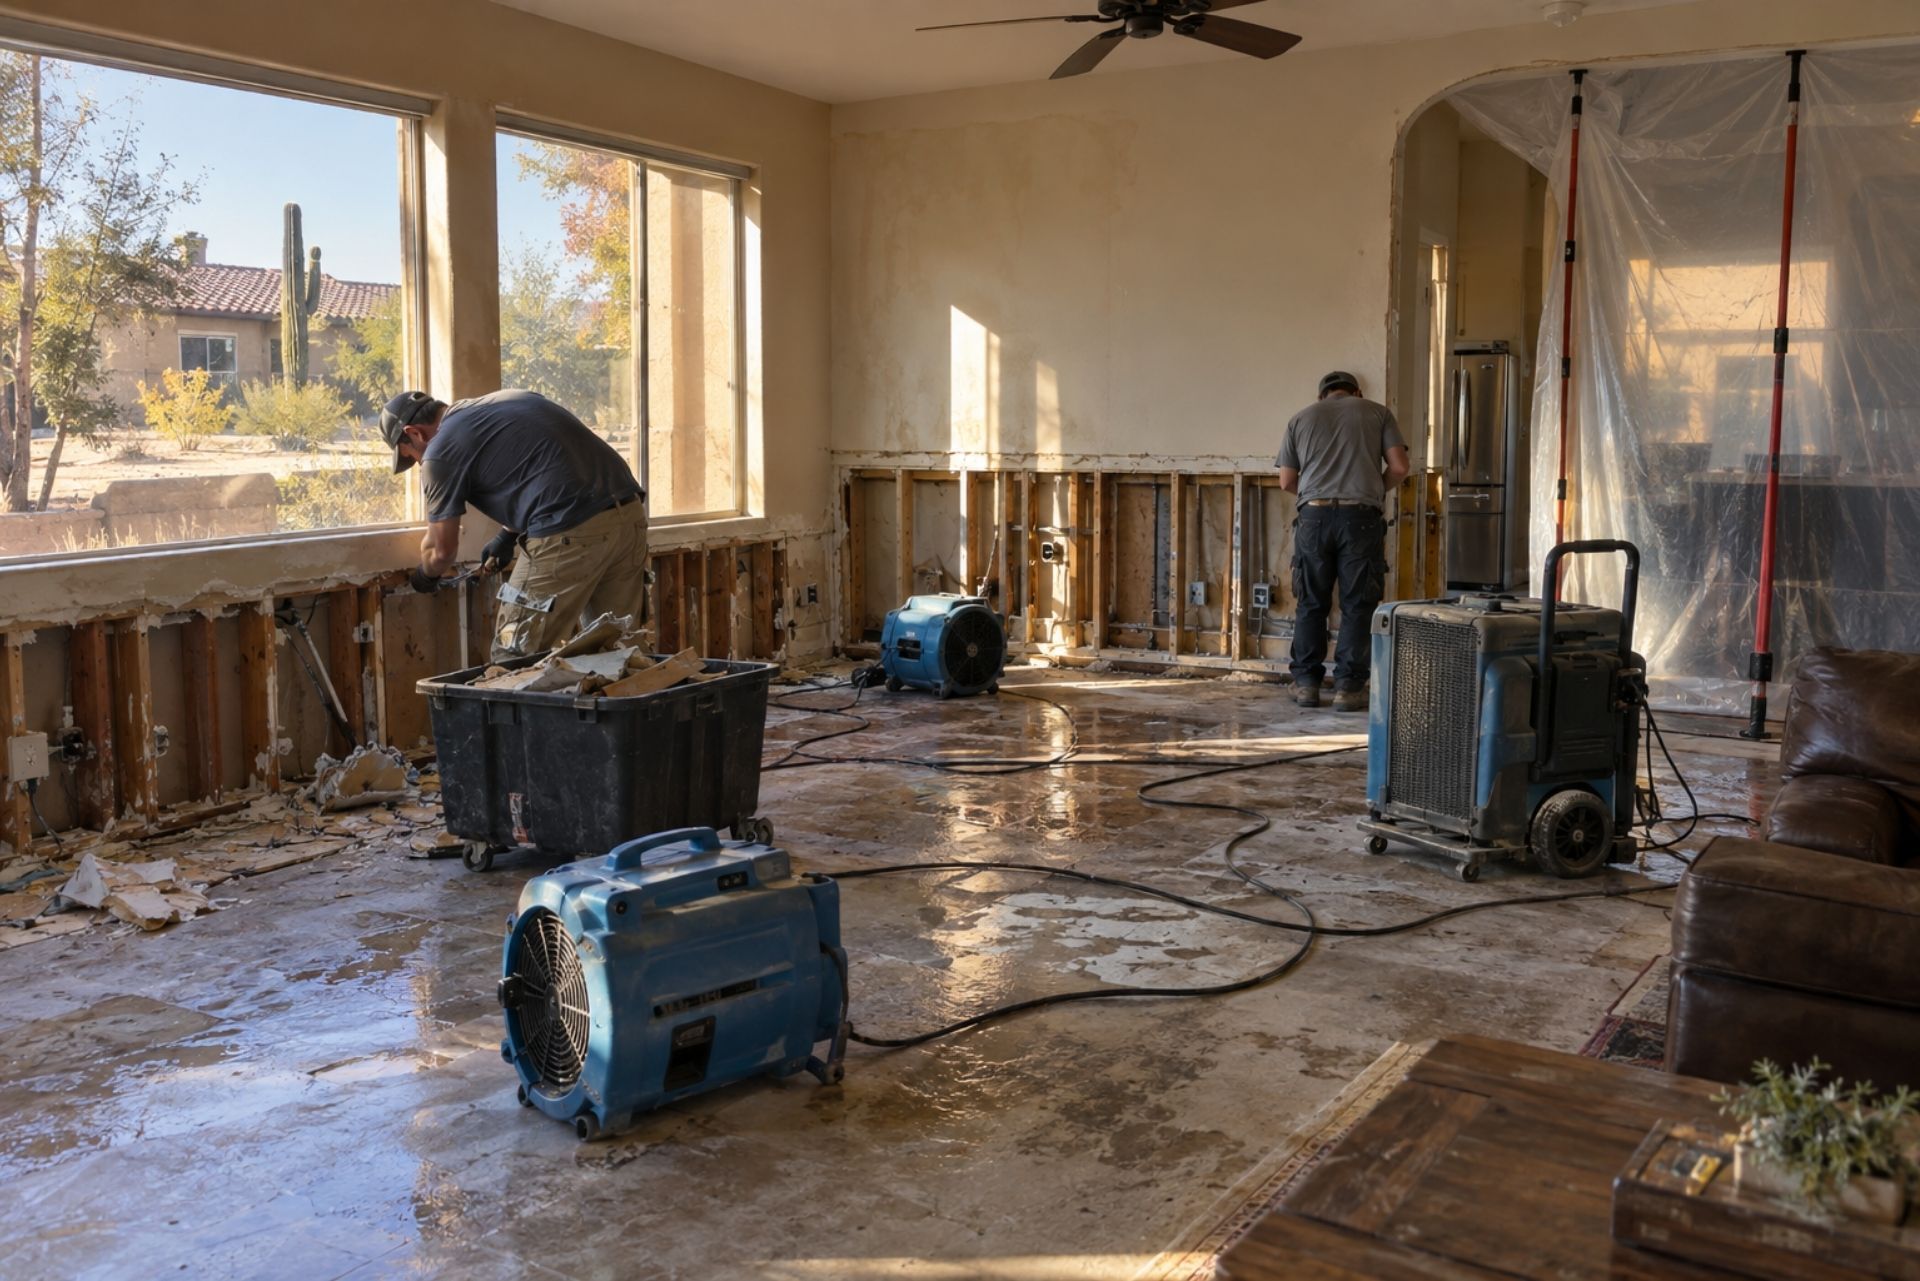
Arizona requires most employers to carry workers' compensation insurance, and restoration work is among the higher-risk classifications. Your crews are entering fire-damaged structures, working around standing water, handling chemical treatments, and operating heavy extraction equipment. Injuries happen, and without proper workers' comp coverage, you're personally liable for medical bills, lost wages, and rehabilitation costs.
Arizona's workers' comp system is a no-fault system, meaning employees don't need to prove you were negligent to receive benefits. That protects both your workers and your business from drawn-out litigation. Classification codes matter here: make sure your policy reflects restoration-specific work rather than general construction, as misclassification can lead to audits and premium adjustments that hit your cash flow hard.
There's also a major regulatory shift to be aware of. Arizona SB1206, effective September 12, 2026, prohibits adjusters from participating directly or indirectly in the repair of property they're adjusting. The law also bars contractors from paying or advertising to pay a policyholder's insurance deductible and prohibits soliciting services while an emergency response is active. If your business model has relied on any of these practices, you'll need to adjust before the effective date to avoid penalties.
Protecting Your Assets: Bailee's and Inland Marine Coverage
Restoration contractors routinely take possession of clients' personal property: furniture, electronics, clothing, documents. The moment those items leave the client's home, you're responsible for them. Bailee's coverage protects you if those items are damaged, lost, or stolen while in your care, custody, or control.
This is one of the most commonly overlooked coverages in the restoration industry. A standard GL policy typically excludes property in your care. Without bailee's coverage, if a fire breaks out at your storage facility or a pack-out van is broken into, you're paying out of pocket to replace everything.
Inland marine insurance covers your own equipment and tools while they're in transit or at a job site. Restoration equipment is expensive: commercial dehumidifiers, air scrubbers, thermal imaging cameras, and moisture meters can represent tens of thousands of dollars in assets. Inland marine policies cover these items regardless of location, which matters when your gear moves between multiple job sites daily.
Common Questions About Restoration Insurance in Arizona
Do I need pollution liability even if I only do water damage work? Yes. Water damage jobs frequently involve sewage, gray water, or mold that develops after the initial loss. A pollution liability policy covers claims from these biological and chemical hazards that standard GL excludes.
How does SB1206 affect how I market my restoration business? You can no longer solicit work during an active emergency event, and you can't offer to cover a homeowner's deductible as an incentive. Review your marketing materials, website language, and sales scripts before September 12, 2026.
What's the difference between bailee's coverage and inland marine? Bailee's covers your clients' property while it's in your possession. Inland marine covers your own equipment and tools. You likely need both.
Will my workers' comp rates go up if I add mold remediation services? Possibly. Mold work carries different risk classifications than standard water mitigation. Talk to your agent about how adding services affects your experience modification rate and premium.
How long does it typically take to get paid on restoration claims in 2026? Carrier payment delays have stretched to 60 to 90 days as a standard timeline. Build this into your cash flow planning and consider a line of credit to bridge the gap.
Building a Robust Risk Management Strategy
Insurance is only one part of protecting your restoration business. A strong risk management approach reduces claims frequency, which keeps your premiums lower and your experience modification rate favorable.
Start with documentation. Photograph every job site before, during, and after work. Use moisture mapping software to create a verifiable record of conditions. These records are your best defense if a client disputes your work or an insurer questions a claim.
Training is equally critical. IICRC certifications aren't just marketing tools: they demonstrate that your team follows industry-standard protocols. If a claim goes to litigation, having certified technicians who followed documented procedures puts you in a much stronger position. Pair this with written safety programs covering PPE requirements, confined space entry, and electrical hazard protocols for water-damaged structures.
That said, risk management also means understanding your contracts. Your subcontractor agreements should include indemnification clauses and proof of insurance requirements. Your client contracts should clearly define the scope of work, limitations of liability, and payment terms. Vague contracts lead to disputes, and disputes lead to claims.
Selecting the Right Policy for Your Restoration Business
Finding the right insurance program for your Arizona restoration company means working with an agent or broker who actually understands the restoration industry. A generalist insurance agent may not know the difference between a Category 2 and Category 3 water loss, and that knowledge gap shows up in the coverage they recommend.
Ask potential agents specific questions. Can they place a combined professional liability and pollution policy? Do they have access to markets that offer bailee's coverage with limits appropriate for contents restoration? Are they familiar with Arizona's new SB1206 requirements and how they affect your operations?
Price matters, but coverage gaps matter more. A policy that saves you a few thousand dollars annually but excludes mold, pollution, or contents in your care is a liability waiting to happen. Get quotes from at least three agents who specialize in contractor or restoration insurance, and compare not just premiums but exclusions, sub-limits, and deductible structures.
Your restoration business faces risks that are specific to Arizona's climate, regulatory environment, and disaster patterns. The right insurance program protects you from monsoon flooding claims in August, wildfire restoration disputes in July, and mold liability year-round. Don't wait for a claim denial to find out what your policy actually covers. Review your coverages now, close the gaps, and make sure your business can survive the next loss - not just your client's.
About The Author:
Taylor Whatcott
As President of Wilde Wealth Insurance Services, I’m committed to providing trusted protection for both families and businesses across Arizona. Our independent team works with top-rated carriers to deliver tailored, comprehensive coverage—making insurance simple, accessible, and hassle-free.
Contact Us
Commercial Coverage Solutions
Protect Your Business with the Right Insurance
We offer customized insurance solutions to safeguard your business from financial risks. Our policies provide protection for property, employees, and liability concerns.
Commercial Property Insurance
Safeguards buildings, equipment, and inventory from damage or loss.
Professional Liability Insurance
Covers claims of negligence, errors, or omissions in services.
Cyber Liability Insurance
Protects against data breaches, cyberattacks, and online threats.
Who We Protect
Insurance Solutions for Your Industry
We specialize in providing tailored coverage for businesses in key industries. Our policies are designed to meet industry-specific risks and ensure complete protection.
Protection for Your Home & Assets
Reliable Coverage for Life’s Unexpected Moments
We provide personal insurance solutions designed to safeguard your home, vehicle, and financial well-being. Our policies ensure you and your loved ones are protected.
What Our Clients Say
Real Feedback. Real Confidence.
FAQs
Answers to Common Insurance Questions
How do I know which insurance coverage is right for me?
Choosing the right insurance depends on your personal or business needs. Our team evaluates your risks and recommends tailored coverage to protect what matters most.
We work with multiple carriers to provide different policy options. This allows you to compare benefits, limits, and pricing to make an informed choice.
If you’re unsure, we’ll walk you through the options step by step, ensuring you understand your coverage and feel confident in your decision.
Why should I choose an independent insurance agency like Wilde Wealth?
As an independent agency, we are not tied to a single insurance provider. This means we can compare multiple policies to find the best coverage at the best price.
Our goal is to advocate for you, ensuring you receive personalized service and expert advice tailored to your situation.
Unlike direct insurers, we offer ongoing support, helping you with claims, policy changes, and future coverage needs.
Can I bundle multiple insurance policies to save money?
Yes! Bundling policies like home and auto can lead to significant savings. Many carriers offer discounts for combining multiple coverages.
Bundling also simplifies policy management, with a single point of contact and streamlined renewals.
We help you explore bundling options to ensure you get the best value while maintaining the protection you need.
What factors affect my insurance rates?
Insurance rates are influenced by factors such as coverage limits, location, claims history, and risk exposure. Personal insurance may consider credit scores, driving history, and home value.
For businesses, factors like industry type, employee count, and annual revenue can impact pricing. Each carrier evaluates risk differently.
We shop multiple providers to find the best balance of coverage and cost, ensuring you don’t overpay while staying fully protected.
How does Wilde Wealth Insurance Services help business owners?
We provide customized business insurance solutions to protect against liability, property damage, employee-related risks, and cyber threats.
Our team works with a range of industries, including contractors, restaurants, and real estate professionals, to offer tailored policies.
From small startups to established enterprises, we help business owners minimize risks and keep operations running smoothly.
What happens if I need to file a claim?
Filing a claim is simple with our support. Contact us first, and we’ll guide you through the process, ensuring all necessary information is submitted correctly.
We work directly with your insurance carrier to expedite the claim, keeping you informed at every step.
Our team is here to advocate for you, making sure you receive a fair and timely resolution.
Latest Articles & Insights
Stay Informed with Expert Insurance Advice
We provide valuable insights to help you make informed insurance decisions. Explore our latest articles on coverage options, industry trends, and risk management tips.
Contact Us